I approached Walmart MoneyCard® as a daily finance tool rather than something to open once and forget. The first impression is straightforward: this is a free app from Green Dot built around managing the Walmart MoneyCard, with a focus on making routine money tasks easier to handle from a phone. Its store summary promises a better banking experience, but the more useful question is whether it remains practical after the first week, when the novelty of a new financial app has worn off.
My answer is cautiously positive. The app can earn a regular place on your phone if you already use the Walmart MoneyCard and want a convenient way to keep an eye on your balance and card activity. It is less compelling for someone looking for a full replacement for a traditional bank, a broad budgeting platform, or a financial app that brings every account into one dashboard. That distinction matters because a focused prepaid-card companion can be useful precisely because it does not try to do everything.
What the first week feels like
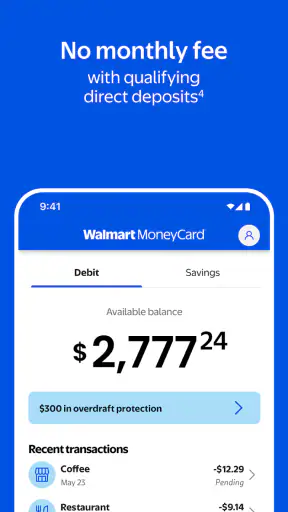
The first week is when the app makes its strongest case. A finance app should reduce uncertainty, and the most valuable early habit is checking your available money before spending rather than guessing. With a card-centered app, that quick check can be more useful than opening a general banking app filled with accounts and menus you do not need.
I found the appeal strongest for people who use the Walmart MoneyCard for controlled spending. It can fit a weekly grocery budget, household purchases, travel spending, or money set aside for a family member. The card itself creates a boundary, while the app gives that boundary a visible place on your phone. That combination is more practical than relying on memory, paper notes, or occasional visits to a website.
The app is free, which lowers the barrier to trying it. It is listed for mature users aged seventeen and over, so it is not positioned as a child-focused money-learning tool. That age positioning also makes sense for the kinds of decisions involved: tracking card activity, checking available funds, and deciding whether a purchase fits the money already set aside.
One detail I would pay attention to during setup is whether the app fits your existing Walmart MoneyCard routine instead of forcing you to create a second system. The best early workflow is simple: open the app at the start of the day or before a planned purchase, check the current picture, and close it. If you turn every check into a long budgeting session, you may create unnecessary friction and stop using it.
A realistic example is a weekend grocery trip. Before leaving home, I would check the card balance, estimate the purchase, and leave a small cushion for an item I may have forgotten. Afterward, I would look at the activity to confirm that the spending matches what I expected. That two-step habit is more valuable than checking repeatedly throughout the day because it connects the app to an actual decision.
The early experience also depends on expectations. This is a finance app, not a general-purpose money coach. It should be judged on how clearly it supports Walmart MoneyCard management, not on whether it replaces a full bank account, an investment service, or a dedicated expense-analysis application. People who understand that scope are more likely to appreciate its focused design.
The app has reached more than half a million installs, and its average rating is 3.7 from around 3,700 ratings. Those figures suggest that it has a meaningful user base but also that the experience is not universally smooth. I would treat that as a reason to test the everyday workflow carefully rather than as a reason to dismiss it. Finance apps are especially sensitive to login problems, unclear activity, or delays that may feel minor in another category but become stressful when money is involved.
Who gets the most from the focused approach
The strongest match is someone who already relies on the Walmart MoneyCard and wants a dedicated control panel. It may also suit a person who prefers separating spending money from money held elsewhere. For example, keeping a fixed amount for groceries or discretionary purchases can make a prepaid card easier to monitor than using one account for every bill and impulse purchase.
I can also see value for users who want a simple routine without the complexity of linking multiple financial institutions. A focused card app may be less intimidating than a financial dashboard that asks you to organize accounts, categories, goals, and recurring transactions before it becomes useful. Here, the card is the center of attention, which can make the first useful action obvious.
On the other hand, I would skip it if your main goal is detailed household budgeting across several accounts. If you need long-term spending categories, investment tracking, bill planning, or a broad view of cash flow, a dedicated budgeting app or a conventional bank application may be a better primary tool. You could still use this app for the card itself, but it should not be expected to solve a different problem.
Why it can remain useful month after month
The lasting value of a finance app rarely comes from exciting features. It comes from removing small points of uncertainty often enough that checking becomes automatic. For this app, recurring value depends on whether the Walmart MoneyCard is part of your real spending system. If the card is used regularly, the app has a clear reason to stay installed. If the card sits unused, the app will probably fade with it.
I would build a monthly routine around three moments: before adding money to the card, before making an unusually large purchase, and after reviewing recent activity. That is more sustainable than opening the app without a purpose. The first moment helps you decide how much spending money to place on the card. The second protects against using the card for a purchase that would consume too much of the available amount. The third helps catch habits that are easy to overlook when several small purchases accumulate.
This workflow gives the app a job beyond displaying a balance. It becomes a checkpoint between intention and spending. That is a subtle but important advantage of a card-specific tool: the limit can make financial decisions feel concrete. A broad account view may show that money exists somewhere, while a prepaid-card balance shows what is available for this particular spending purpose.
Another useful habit is separating review from reaction. If I notice a purchase I had forgotten, I would not immediately assume the app is wrong or the transaction is fraudulent. I would first compare the timing, the amount, and what I bought that day. If something still looks unfamiliar, I would then use the appropriate support or card-security process rather than repeatedly refreshing the screen. This keeps the app from becoming a source of anxious checking.
The current version is 2.7.0, and the app requires Android 9 or newer. That makes compatibility an important practical check before committing to it as a primary money tool. Android users on older software will need a different way to manage the card, and anyone using an older phone should consider whether updating the operating system is realistic before building a new financial habit around this application.
For month-to-month use, I would also keep another secure record of important financial information. That does not mean duplicating every transaction manually. It means knowing where you would look if the app were temporarily unavailable, your phone battery died, or you needed to compare card activity with a receipt. A mobile finance app is convenient, but convenience should not become the only place you can reconstruct what happened with your money.
The trade-off against usual alternatives
Compared with a traditional bank app, this experience is narrower but potentially easier to understand if your spending is centered on the Walmart MoneyCard. A bank app usually makes more sense for checking deposits, moving money among accounts, paying bills, and seeing a broader financial picture. The Walmart MoneyCard app is more attractive when the card itself is the main object you need to monitor.
Compared with a budgeting app, it is likely to feel less analytical. Budgeting tools are designed to show patterns across categories and time, while a card companion is better suited to immediate awareness of the money attached to that card. I would choose the latter for a controlled spending pocket and the former for understanding the whole household budget.
Compared with managing a card only through a browser, a mobile app earns its place through convenience. A phone is usually closer when you are standing in a checkout line or deciding whether to make a purchase. That convenience is meaningful only if the app opens reliably and presents the information you need quickly. If checking the card becomes a slow, frustrating process, the browser or another financial tool may feel more dependable despite being less convenient.
The important trade-off is focus versus coverage. This app can be easier to maintain because it has a specific purpose, but that same focus means it may leave you wanting a second tool for broader planning. I would not see that as a flaw by itself. The mistake would be treating a card manager as a complete financial command center and then blaming it for not offering the structure of a budgeting service.
Maintenance, friction, and the reasons people stop using it
The maintenance burden is modest when the app is used with a clear routine, but finance apps demand more discipline than entertainment apps. You need to keep access details secure, pay attention to activity, and avoid assuming that a displayed balance answers every question about your overall finances. The app can simplify monitoring, but it cannot make financial decisions on your behalf.
My preferred maintenance pattern would be brief and consistent. Check before planned spending, review after unusual activity, and do a more deliberate look once a month. That schedule avoids two opposite mistakes: never checking until a problem appears, or checking so often that the app becomes a source of stress. The goal is dependable awareness, not constant surveillance.
One source of fatigue is repetition. If every opening shows information you already know and you are not using it to make a decision, the habit will weaken. The solution is to attach the app to a specific trigger, such as leaving for a large shopping trip or reviewing spending on the same day each month. A trigger gives the app a place in your routine rather than asking you to remember it randomly.
Another source of fatigue is using the card for too many unrelated purposes. A prepaid card can be easier to understand when it has one clear role. If you use it for groceries, subscriptions, travel, gifts, and emergency purchases without any separation, the balance may become harder to interpret. The app can show activity, but you still need a personal rule for what the card is meant to fund.
There is also a psychological trade-off. Seeing a balance can create confidence, but it can also encourage spending simply because money appears available. I would treat the displayed amount as a ceiling for that card, not as a recommendation. Before a purchase, subtract the expenses you have already promised yourself and keep a cushion. That small mental step prevents the app from turning visibility into false permission.
Users should also be realistic about support expectations. When a finance application presents an unfamiliar transaction or a problem accessing the account, the app is only one part of the solution. You may need to follow the card provider’s established process rather than expecting the screen itself to explain every situation. This is one reason I would avoid making the app the sole record of important information.
The mature age rating is another reminder that this is a personal finance product, not a casual utility for every household member. If several people share responsibility for spending, agree on the card’s purpose and review routine outside the app. A clear household rule will do more to prevent confusion than simply giving everyone access to the same balance.
When another option is the better choice
I would choose a traditional bank app first if you need a complete view of direct deposits, savings, bills, transfers, and other accounts. I would choose a dedicated budgeting tool if your biggest challenge is discovering where money goes across the entire month. I would choose neither as a replacement for this app if the Walmart MoneyCard is the spending instrument you actively use and quick card visibility is your main need.
I would also hesitate to rely on it if your phone cannot run Android 9 or newer, because compatibility is not a minor detail for a money-management tool. In that situation, the practical choice is the management method that gives you reliable access to the card, even if it is less convenient than a modern app.
Finally, I would skip making it a daily habit if you do not use the Walmart MoneyCard often enough to justify another financial login. Installing a focused app is not automatically better than keeping one broader tool. Every additional account and notification can add mental overhead. The right question is whether this app removes a recurring problem you actually have.
My long-term verdict
After the first-week appeal fades, Walmart MoneyCard® earns lasting space only when the card has a defined role in your spending. In that situation, the app’s value is practical rather than flashy: it gives you a direct place to check the money connected to the card, supports a simple pre-purchase routine, and can make controlled spending easier to maintain.
I like the focused purpose, the free entry point, and the fact that it does not need to become an all-purpose financial system to be useful. Green Dot’s app is most convincing when I treat it as a small daily checkpoint rather than a complete banking replacement. That approach also makes its limitations easier to accept.
The average rating of 3.7 across roughly 1,900 written reviews points to a mixed experience, so I would test the core tasks early: access the account, check the available money, review activity, and see whether those actions fit naturally into your routine. If they do, the app can become a dependable companion for the Walmart MoneyCard. If they feel slow, confusing, or unnecessary, there is little reason to keep another finance app competing for attention.
My final recommendation is therefore specific. Use it if you want a dedicated mobile view of a Walmart MoneyCard and are willing to maintain a short, regular checking habit. Pair it with a broader budgeting method if you manage several accounts. Skip it if you need full-service banking, detailed financial planning, or a tool that works on an older Android device. Its recurring value comes from clarity and routine, not novelty—and for the right cardholder, that is enough to justify keeping it installed.


